Commercial
Private Client
Independent counsel for the insurance decisions that matter most.
Simpson | McCrady provides premier risk management and insurance solutions for commercial businesses and high-net-worth private clients across Pennsylvania and beyond. Founded in 1911, the firm combines over 100 years of expertise with a personalized, client-first approach to reduce and transfer risk exposures.
Speak with an AdvisorIndependent Insurance Counsel, Pittsburgh & the Mid-Atlantic
Not sure where to start? Get an honest opinion.
Two practices. One standard of counsel.
Commercial programs built around how your Pittsburgh-area business actually operates, not how an off-the-shelf policy assumes it does.
Property & Casualty
From manufacturing facilities and commercial real estate to technology offices, professional service firms, schools, and nonprofit campuses across Pittsburgh, Western PA, and the Mid-Atlantic, we build property and casualty programs that reflect your actual exposure, not a template designed for a different industry entirely.
Management Liability
Directors and officers, employment practices, fiduciary liability, and cyber risk don't fit neatly into a standard commercial package. For technology firms, private equity-backed companies, professional service firms, and institutional organizations in Pittsburgh and the Mid-Atlantic, we structure management liability programs with the precision the exposure demands.
Specialty Programs
Entertainment and broadcasting operations, schools, nonprofits, and niche manufacturing exposures require access to specialty carriers and surplus lines markets. We have those relationships, built over decades in the Pittsburgh and Mid-Atlantic market, and we know how to use them when standard market appetites run short.
Specialized coverage for the assets and exposures that standard carriers are not built to handle.
Homeowners & Estates
Your primary residence and secondary properties carry exposures that standard carriers are not structured to handle. We build homeowners and estate coverage that reflects the true replacement value of what you've built, so a claim settlement doesn't reveal a gap that no one disclosed at placement.
Collections & Fine Art
Fine art, jewelry, wine, antiques, and curated collections require specialized valuation and agreed-value coverage, not a rider on a standard policy. Our advisors work with leading specialty carriers to ensure your collection is covered at full market value, with no depreciation applied at the time of a claim.
Recreational Vehicles & Watercraft
Aircraft, yachts, classic cars, and motorcycles require coverage structures that account for seasonal use, agreed value, and liability exposure well beyond what an auto or homeowners policy provides. We manage that complexity so you can focus on the experience itself.
Personal Liability & Umbrella
HNW individuals and family offices face liability exposures that standard umbrella limits don't address. We structure personal liability and excess umbrella programs, including domestic staff coverage and trust and estate liability, sized to your actual risk profile, not a generic bracket.
The advantages of staying independent
We aren't owned by a national brokerage, and our strategy isn't set by a private equity firm. That independence is why our advice has held up for over 100 years.
Still Independent
No outside owner deciding what your renewal has to produce.
A Century On
Perspective across every market since 1911.
Claim Advocates
A named advisor, never a call center or 1-800 number.
Relationship-Led
Often the same family, across generations.
Every account is different. Let's build yours.
Case studies
Rebuilding After the Unthinkable
When two of our clients experienced a devastating house fire, everything changed in an instant. Beyond the physical loss, they were faced with uncertainty, stress, and the overwhelming task of rebuilding.
This case study shows what truly matters in those moments: a responsive, compassionate insurance agency that stands beside you every step of the way. From immediate support to navigating the claims process and helping turn a damaged house back into a home, this story highlights the power of advocacy, communication, and trust.
Watch the video to see how support makes all the difference.
Private To Public
Simpson | McCrady became the broker for a startup business in the late 2000’s who had ultimate plans to go public. Through our risk mapping analysis and strategies to avoid, mitigate, transfer, and accept risk, we assisted the CFO and CRO in their efforts to plan for and stage a very successful IPO. The culmination of this strategy helped the client obtain significant advantage in the pre and post IPO Management Liability structure and cost including full road show coverage as well as post IPO securities litigation.
Long Standing Partnership
Through a strategic acquisition in 1997, Simpson | McCrady obtained a non-profit client who had first engaged the acquired brokerage firm in 1910. Through the last 22 years (and 87 prior), Simpson | McCrady has continued to support this client with outsourced risk management, board service, and financial support/fundraising. Over the last 22 years, the client’s total cost of risk has declined incrementally, a Simpson | McCrady partner chaired the Board of Directors for 6 years, and we have raised well in excess of $400,000 in financial support.
Planning for Tomorrow
A client had recently worked with their estate planning attorney to implement a family trust which had ownership in their secondary residence. Over the last few years, they had also recently sold their family business which caused a liquidity event. The middle market carrier that they were with through a direct writer incorrectly wrote their secondary home in the name of the trust on a commercial policy. With this policy they were incorrectly insuring the home and overpaying for the risk. The company also could not address the increased excess liability limits that the family needed at a reasonable cost.
We were able rewrite the client’s policies appropriately with a high net worth carrier that had the expertise and understanding to appropriately address the trust for liability and property coverage and also provide adequate excess liability limits to protect their tangible assets, net worth, and future earnings with more adequate pricing.
Find out what independent counsel could do for you.
Your advisor is a named person, not a service center.
At Simpson | McCrady, client relationships are held by individual advisors with the experience and authority to act on your behalf. Our senior team brings an average of 25 years of specialized experience across commercial and private client lines, and they answer their own phones.
Chris McCrady
Principal & CEO
S. Clayton Saftner
President & COO
CFO · Regional manufacturer
They understood our operation better than carriers we'd worked with for twenty years.
A Private Client family · Fox Chapel, PA
When a pipe burst over the holidays, our advisor had an adjuster at the house before we'd finished cleaning up. They treated it like it was their own home.
Private Client · Sewickley, PA
Three generations of our family, the same trusted firm. They simply know our story.
Speak with a named advisor, not a call center.
Perspective worth keeping

SEC Exam Priorities for 2027: What RIAs Should Expect, and Where E&O Insurance Fits
The SEC's 2027 exam priorities focus on private credit, fee conflicts, Reg S-P and AI. Here is what RIAs should expect, and where E&O and D&O fit.
When I was a financial lines underwriter, we always paid close attention when the SEC's exam priorities dropped. As evaluators of risk, it helped to understand what the regulator was thinking in the context of the current market, new regulations and emerging vulnerabilities.
The list worked as a preview. What examiners focus on this year tends to resurface later in deficiency letters and, sometimes, client claims. When a firm's business lined up with the priorities, we read its regulatory history twice.
The SEC released its fiscal year 2027 priorities on October 23, alongside a new Exam Handbook published earlier in the month. Here is what stands out for advisers, with our recommendation for each.
What the SEC will look at in 2027
Economic conflicts
SEC priority: New this year. Examiners will prioritize fee rebates, fee and expense calculations and cash management.
Our recommendation: Check a few client invoices against the advisory agreement each quarter. It catches most billing errors before an examiner does.
Private credit and illiquid products
SEC priority: Examiners will ask whether private fund loans, BDCs and private company stakes held through special purpose vehicles fit the client, especially retail and older investors.
Our recommendation: For each client holding them, keep a note on file covering their liquidity needs and how lockups and valuation were explained.
Firms that are new to exams or have changed
SEC priority: Never-examined advisers, firms that grew through acquisitions and firms with dispersed branches will get a closer look at whether compliance kept pace.
Our recommendation: Run an outside mock exam to find the gaps first.
Regulation S-P
SEC priority: The amended rule now applies to every registered adviser, and examiners will test incident response and vendor oversight.
Our recommendation: Hold a yearly tabletop exercise to see whether the written plan works, and keep a vendor list noting each provider's breach notice duty so the 72-hour requirement stays manageable.
AI
SEC priority: The SEC calls it "super intelligence." Examiners will ask whether a firm's public claims about AI hold up and how ready it is for deepfake fraud.
Our recommendation: Keep a list of approved tools, and confirm every wire or payment change by calling a number already on file. That callback is exactly what a deepfaked voice is built to get around.
Private credit reaches past the RIA
This is the item I would watch most closely, because it touches nearly every financial institution we work with. Fitch's U.S. private credit default rate hit a record 6.3% in the third quarter, and on November 9 the Dallas and New York Federal Reserve Banks opened a pilot survey of private credit lenders, citing limited visibility into the market.
The exam question (does this product fit this client?) is the same one a client's attorney asks after a fund limits withdrawals. If I were underwriting an adviser today, one of my first questions would be how much of the client base sits in semi-liquid vehicles, and how the firm documented the fit.
Does E&O insurance cover an SEC exam?
Usually not the exam itself. Under the new Handbook, records should generally be ready within 24 hours (staff usually allow two weeks for the first request), and most exams close with a deficiency letter and a 30-day response window. Most adviser E&O and management liability forms define a claim to include a formal investigation, typically one started by a subpoena, Wells notice or formal order. A routine exam generally falls outside that definition, so the cost of responding usually stays with the firm.
Some forms go further, with endorsements for informal inquiries, pre-claim investigation costs or self-reporting, often sublimited. That matters most if a finding is referred to Enforcement.
The exposure also reaches individuals. When an exam finding turns into a client claim or an enforcement matter, portfolio managers and the CCO can be named personally over suitability calls on BDCs or private fund stakes. That brings D&O or management liability coverage into play alongside E&O. Some advisers carry both on one combined form, and others carry separate policies with different terms. In either case, look at who counts as an insured person and whether individuals have a limit of their own.
Five questions for your renewal
- How does the policy define a claim? Check whether it reaches informal inquiries or only formal proceedings, and whether an exam finding can be reported as a circumstance.
- How are fines, penalties and disgorgement treated? Many forms carve them out of covered loss or cover certain civil penalties only where the law allows.
- Do product exclusions match client accounts? Some adviser E&O forms limit claims tied to non-traded REITs, BDCs or alternatives.
- Does the cyber policy respond to Reg S-P? Look at regulatory coverage, notification costs and breaches at vendors holding your client data.
- What is on the endorsement schedule? AI exclusions have started appearing on management liability forms, and they do not show up on a certificate of insurance.
Underwriters are reading the same list you are. A renewal application that already speaks to your exam history and private credit exposure tends to make for a smoother conversation.
Levi McCrady is an Account Executive at Simpson | McCrady in Pittsburgh, where he works with investment advisers, private equity firms, family offices and other financial institutions. Before joining the firm, he spent five years as a financial lines underwriter at Chubb in New York. Reach Levi at lcmccrady@simpson-mccrady.com or 412.999.0204.
This article is general information and is not legal advice. Coverage depends on the terms, conditions and exclusions of each policy.
Five Nonprofit D&O Insurance Questions Every Board Should Ask Before Year-End
Can nonprofit board members be sued personally? That was the question that got the biggest reaction when Derek Gallagher spoke on a nonprofit insurance panel last month. The short answer is yes. Board members, officers and volunteers can be named in a lawsuit alongside the organization, and even a claim without merit has to be defended.
I've spent more than six years at Simpson | McCrady as an Account Executive, working with nonprofits of every size since day one. I'm a member of the Special Needs Consortium, where I serve on the board and the education committee. In those roles I've seen firsthand why nonprofit D&O insurance (Directors and Officers coverage) matters.
Recently I sat on a panel with respected peers, speaking with executive directors, staff, board members and donors. The question that got the biggest reaction was a simple one: can board members be sued personally?
Can nonprofit board members be personally sued?
Yes. Board members, officers, staff and volunteers can be named in a lawsuit alongside the organization, by employees, donors, regulators, creditors and even the people you serve. Even a claim without merit has to be defended, and legal bills hit small budgets hardest. D&O insurance is designed to pay defense costs, settlements and judgments when leaders are accused of a wrongful act, such as an error, a misleading statement or a breach of duty. That's why the details of your policy matter. As boards gather for year-end reviews and 2027 planning (in between fundraising campaigns and holiday functions), here are five questions I'd want every board to bring to the table.
1. Who counts as an insured?
A policy only protects the people it names. Many include current and former board members, officers, employees with certain managerial responsibilities, volunteers, committee members and the organization itself. Check whether yours does.
Two myths come up here. Volunteer protection laws limit some personal liability, but they don't stop a lawsuit, pay legal fees or protect the organization. And bylaws that promise to indemnify (reimburse) the board are only as strong as your bank account.
2. Is employment practices liability included, and at what limit?
Employees are the most common source of nonprofit D&O claims, from wrongful termination to discrimination, harassment and retaliation. Employment practices liability (EPL) coverage is built for these claims.
Some nonprofit management liability policies include EPL. Others sell it separately, and some programs lack it entirely. Ask whether you have it, what the limit is, and whether it's shared with the rest of the policy. Some policies also extend this coverage to claims brought by volunteers, so check whether yours does. A small staff doesn't mean small exposure.
3. Does everyone share one limit, and do legal fees come out of it?
This one surprises boards most. Most D&O policies have an aggregate limit, the most they'll pay for all claims combined in a policy year. In many policies, the organization, its leaders and any EPL claims all draw from that single limit, and defense costs usually reduce it rather than sitting on top of it.
In practice, a $1 million policy that spends $400,000 on defense has $600,000 left for a settlement, a judgment or the next claim. When leaders' interests differ and each needs their own attorney, that limit shrinks even faster. For illustration, picture an animal shelter whose donors sued the board over how it represented its finances. Three lawsuits followed, with defense costs over $530,000. On a $1 million shared limit, that alone would use more than half.
Ask your broker whether your limit fits your size, the number of people insured and your budget. Options can include separate limits for D&O and EPL, or an added limit just for individual leaders. Also ask about your retention, the amount the organization pays before the policy kicks in, much like a deductible. Make sure it's one your budget can handle.
4. Who handles the defense, and when are legal bills paid?
Some policies give the insurer a “duty to defend,” meaning it appoints and manages the attorneys. Others let you choose counsel and reimburse covered costs. Ask how much say your board has.
Timing matters too. Ask whether defense costs are advanced as bills come in or only reimbursed later, which can take months. For a nonprofit with tight cash flow, fronting those fees pulls money from programs and payroll. One catch: if a claim turns out not to be covered, advanced costs may have to be repaid.
Finally, know the settlement rules. Most policies require the insurer's consent before you settle or take on legal costs, and some include a “hammer clause” that can cap the insurer's payment if your board turns down a settlement it recommends.
5. What's excluded, and what happens if we merge?
Every policy has exclusions worth reading before you need them. Three to watch for:
- Insured vs. insured: excludes or limits claims one insured brings against another, like one board member suing another. Some policies carve back certain claims, such as those by employees.
- Prior or pending litigation: claims tied to lawsuits that existed before a set date are usually excluded.
- Wage and hour: pay and overtime disputes are often excluded or capped.
If a merger or affiliation is on the horizon, talk with your broker before it closes. Many policies then cover only acts that happened before the deal.
Put nonprofit D&O insurance on your next board agenda
Bring these five questions to your next board meeting or year-end planning session. We're happy to review your policy and walk your board through it, no cost, no pressure. Reach me at 724-650-5145 or DGallagher@Simpson-McCrady.com, or visit our management liability page.
This article is a general guide, not legal advice. Every policy and claim is different.
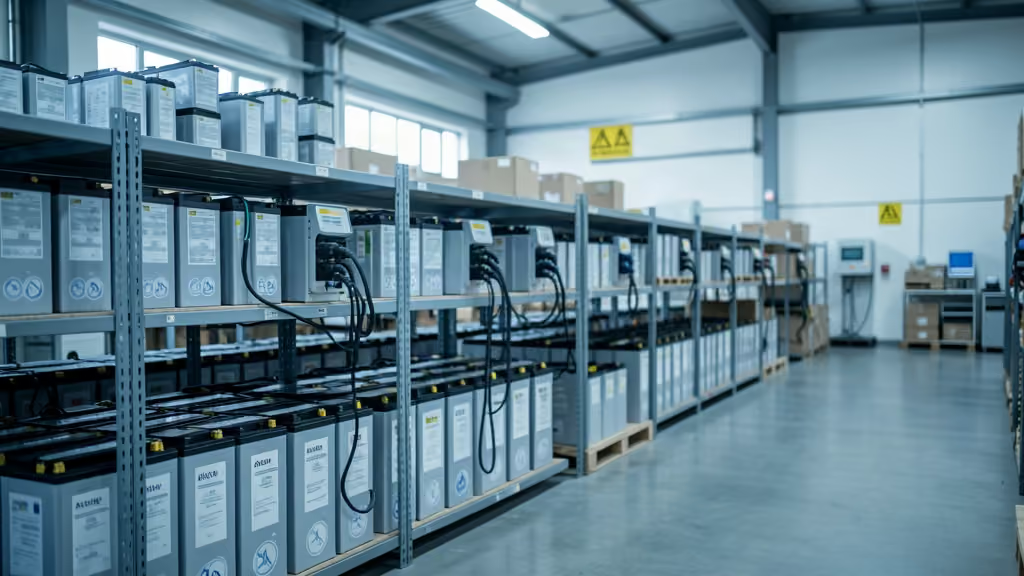
Lithium-Ion Battery Handling & Storage
A best-practice guideline for preparing your facility or home for the safe use and storage of lithium-ion batteries and energy storage systems: how and why cells fail, the fast-shifting regulatory and liability landscape, and configuration-specific controls from a charging bench to a container-scale system.
A best-practice guideline for preparing your facility or home for the safe use and storage of batteries and energy storage systems.
The Growing Risk
Lithium-ion (Li-ion) and lithium-polymer (Li-Po) batteries now power nearly every corner of modern operations: cordless tools and equipment, material-handling fleets, electric vehicles, micro-mobility devices, and the large stationary energy storage systems (ESS) that stabilize power supply and support renewable generation. Their high energy density, long service life, and fast recharging have made them the default choice. Those same qualities, however, concentrate a great deal of energy into a small, chemically reactive package. When a Li-ion battery is defective, damaged, poorly stored, or improperly charged, it can fail violently, releasing intense heat, toxic gas, and a self-sustaining fire that conventional extinguishers struggle to control.
The scale of the exposure is growing with adoption. Since the start of 2025 alone, the U.S. Consumer Product Safety Commission has issued 46 recalls and safety warnings for consumer products powered by lithium-ion batteries, and several high-profile facility fires have reshaped how regulators, fire officials, and insurers view the hazard. For any organization that uses, charges, or stores these batteries in more than trivial quantities, the question is no longer whether to manage the risk, but how thoroughly.
This guideline is a practical roadmap for our clients. It explains how and why these batteries fail, summarizes the emerging legal and regulatory landscape, and lays out configuration-specific best practices for preparing your facility, from a handful of tool batteries on a charging bench to a container-scale energy storage system.
Understanding the Risk
How lithium-ion batteries fail: thermal runaway
Nearly every serious Li-ion incident traces back to a single phenomenon: thermal runaway. It begins when one cell generates more heat than it can dissipate, often because of an internal short from a manufacturing defect, physical damage such as a puncture or crush, overcharging, deep discharge, or exposure to excessive heat. As the cell heats, it ignites its own flammable electrolyte; that heat spreads to adjacent cells, which fail in turn, producing a self-reinforcing chain reaction. Because the reaction generates its own oxygen, these fires are difficult to extinguish, can reignite hours later, and react violently with water where lithium metal is present.
Critically, failure does not happen all at once. It escalates through recognizable stages, and the earlier the failure is detected, the more options remain to intervene.

Beyond fire: toxic and environmental exposure
Li-ion fires are not only a combustion hazard. Burning cells release highly toxic gases, including hydrogen fluoride (HF) and per- and polyfluoroalkyl substances (PFAS, the persistent “forever chemicals”), that can injure the eyes, skin, and respiratory system and require evacuation. Water used to fight a battery fire can become contaminated with heavy metals such as cobalt, nickel, copper, and manganese, creating a risk of soil and groundwater pollution if it is not contained. After the January 2025 Moss Landing energy storage fire in California, which destroyed roughly 55,000 battery modules, EPA soil sampling detected several of these heavy metals at levels exceeding screening standards in the surrounding area.
The emerging legal and regulatory landscape
The regulatory picture is shifting quickly, and it increasingly reaches organizations that merely handle batteries rather than manufacture them. In May 2023, the EPA advised that most lithium-ion batteries on the market today are likely to qualify as hazardous waste under the Resource Conservation and Recovery Act (RCRA) based on their ignitability and reactivity. The agency is now developing a dedicated “universal waste” category for lithium batteries, with a proposed rule anticipated in 2026 and a final rule expected in 2027. At the state level, Extended Producer Responsibility (EPR) programs are expanding. Illinois requirements took effect January 1, 2026, and California has enacted both stewardship-plan obligations (AB 2440) and a point-of-sale recycling fee (SB 1215). Meanwhile, some states impose stricter hazardous-waste thresholds than the federal baseline.
The liability exposure is equally significant. Under the federal Superfund statute (CERCLA), cleanup liability is strict, joint-and-several, and retroactive: facility owners and operators, parties that arrange for disposal or recycling, and transporters can all be named, and even sending a small volume of defective cells to a contaminated site can expose a company to a share of the full cleanup cost. Following Moss Landing, the operator entered a CERCLA settlement in July 2025 to fund a cleanup expected to take two or more years. Organizations once considered removed from battery operations, such as auto dealerships handling EV batteries or retailers managing consumer returns, can now trigger hazardous-waste obligations, and California penalties can reach tens of thousands of dollars per day, with criminal exposure for knowing violations.
Foundations: Selection, Inspection, and Built-In Safeguards
Buy quality; avoid counterfeits
The single most effective way to reduce battery risk is to keep defective cells out of your facility in the first place. Purchase tools, equipment, and batteries from reputable manufacturers whose products are certified to the applicable Underwriters Laboratories (UL) standards, and buy replacement batteries and chargers only from the original equipment manufacturer (OEM) or its authorized vendors. Counterfeit and aftermarket batteries frequently omit the internal safeguards that protect genuine cells and are a leading contributor to failures. Where your application allows, consider lithium iron phosphate (LFP / LiFePO₄) cells, a Li-ion chemistry known for greater thermal stability and lower susceptibility to thermal runaway.
Inspect on arrival and before every use
Establish a quality-control step so a designated employee inspects new batteries on delivery, and personnel check batteries before each use. Remove from service, and dispose of properly, any battery showing bulging or swelling; cracked, broken, or discolored casings; excessive heat during charging or use; hissing; leaking; or smoke or unusual odors. Multimeters and digital or infrared thermometers support periodic, documented health checks. Keep a Safety Data Sheet (SDS) on file for every battery on site; these drive correct storage, handling, and emergency response.
Rely on built-in protections, but not on them alone
Quality Li-ion batteries include layered safeguards: a separator that shuts down ion flow as temperature rises, a pressure-relief vent, thermal interrupts and fuses, overcharge and short-circuit protection, temperature sensors, cell balancing, and a Battery Management System (BMS) that monitors state of charge, temperature, and cell health and can disconnect the pack when it detects an anomaly. These features reduce risk but do not eliminate it; facility controls remain essential.
Preparing Your Facility by Configuration
The right controls depend on how batteries are used and stored. The practices below address the configurations our clients most commonly operate; a summary of key setbacks and standards appears in the table at the end of this section.
General and bulk storage
Charging stations for tools and equipment
Most tool-battery incidents occur during charging. To avoid this:
Energy storage systems (ESS / BESS)
Stationary energy storage introduces the largest concentration of stored energy on many sites and warrants a design-led approach. New systems should be certified to UL 9540 (Energy Storage Systems and Equipment) and evaluated using the UL 9540A test method, which characterizes thermal-runaway fire propagation and informs required spacing, ventilation, and fire protection; battery units should be UL 1973-listed and inverters UL 1741-certified. Installations should follow NFPA 855 (Installation of Stationary Energy Storage Systems) and NFPA 70 (Article 706). For further continuity:
Material-handling equipment (forklifts and pallet jacks)
Electric material-handling fleets increasingly use Li-ion packs with decentralized “opportunity charging” throughout the operation. System best practices for this equipment include:
Electric vehicles and micro-mobility
E-bikes, e-scooters, and hoverboards are a frequent source of facility fires, and many jurisdictions now regulate them; in New York City, for example, e-bikes must be certified to UL 2849. As such, it is recommended that a policy be adopted that outlines the following:
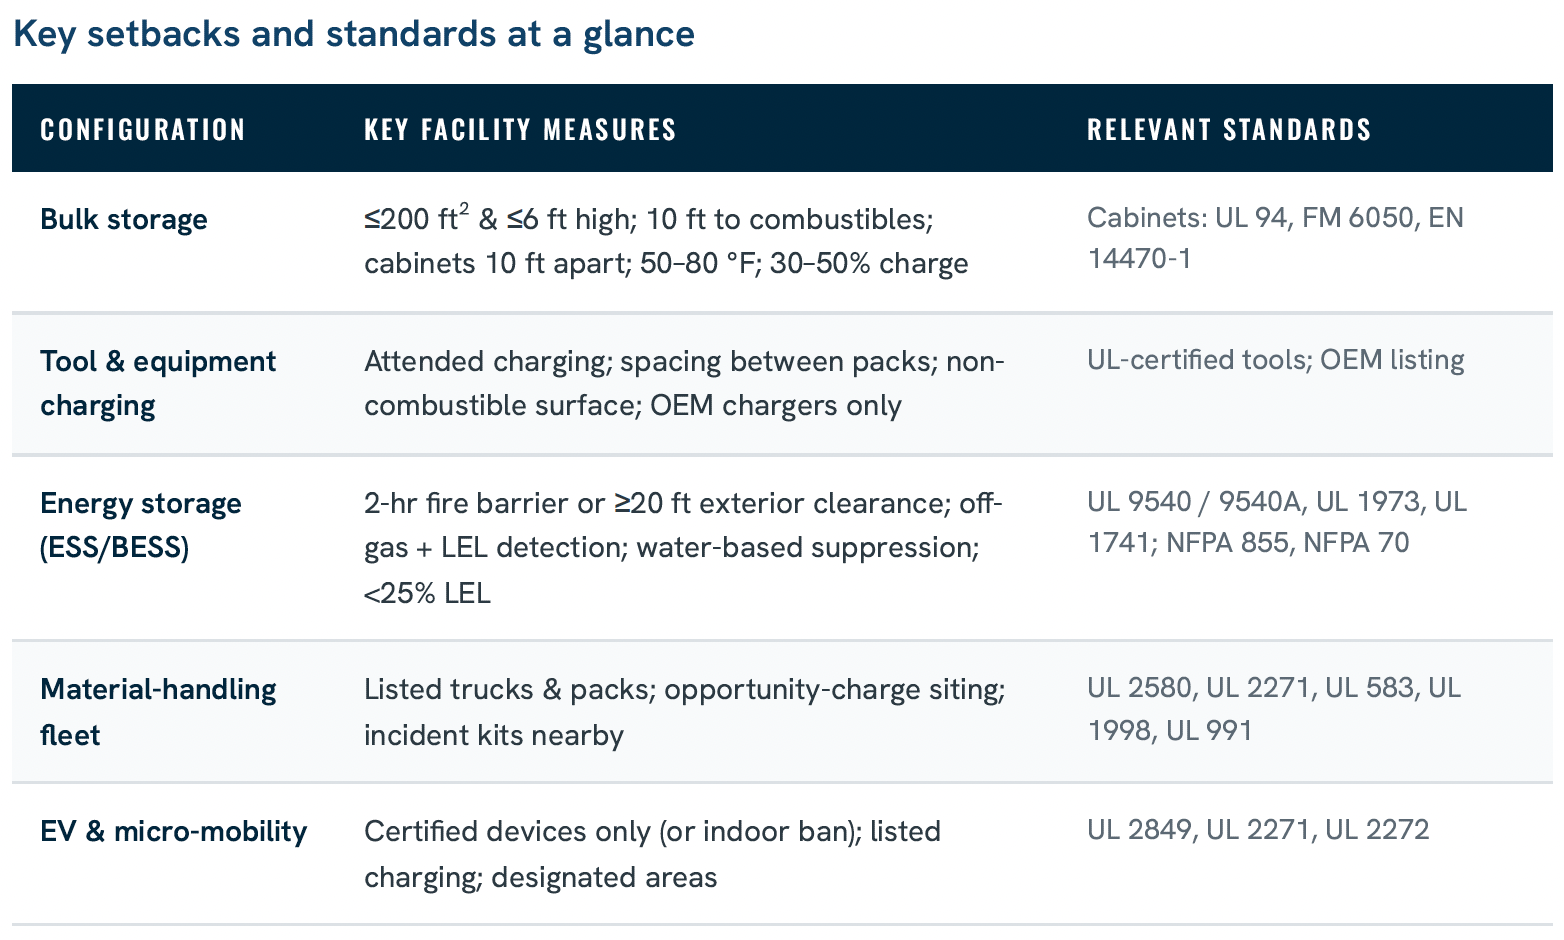
Emergency Response and Incident Readiness
Even well-run facilities should plan for failure. Build a written emergency response plan around the principle that early action and fast evacuation save lives and property. It is heavily recommended that the local fire department be contacted and made aware of the type, configuration, and location of battery systems within your facility. Having their insight and input into the development of your emergency response plan is vital.
Detection and isolation. Train staff to recognize the early signs (unusual odor, discoloration, swelling, excessive heat, hissing, or smoke) and, only if it is safe to do so, to move a suspect battery away from combustibles into a fire-rated isolation container. Keep a pail of sand nearby as a smothering agent.
Small, incipient fires. Because battery fires emit toxic fumes, all untrained personnel should evacuate immediately. Only personnel specifically trained to fight small battery fires should attempt to do so, positioned between the fire and the nearest exit; if the extinguisher is ineffective, smoke becomes heavy, or the responder is at all uncomfortable, they should evacuate. If flames are subdued, submerge the battery in sand or douse with water as directed by the SDS; sand is the safer choice where lithium metal may be present.
Thermal runaway and large fires. No one should attempt to fight a thermal-runaway or large-scale fire. Activate the alarm, evacuate the building, and call emergency services, providing the battery type and size, the location, and any hazardous materials present, and hand the relevant SDS to responders when possible.
First aid. For eye or skin exposure, flush with water for at least 15 minutes and seek medical attention; move anyone exposed to fumes or smoke into fresh air and administer first aid or CPR as needed. Because effects can be delayed, exposed individuals should be evaluated by a medical professional.
Disposal and cleanup. Never place Li-ion batteries in general waste; route them to a certified recycler, and store damaged units awaiting pickup in a non-combustible container located about 25 ft (8 m) from occupied buildings. Provide containment or retention basins to capture contaminated firefighting water, consistent with the environmental exposures described earlier.
Get a quote, or just an honest opinion
Tell us a little about what you're protecting. You'll hear back from a real advisor, not a call center.
Private Client Inquiry